You found the surgeon you want. Maybe they trained at the best program in the country. Maybe they pioneered a specific technique. Maybe your trusted doctor specifically recommended that surgeon. There’s just one problem: they’re not in your insurance network.
Here’s the good news: you can still choose them. There is a path for this.
The No Surprises Act, a new law that took effect in 2022, created something called the Notice and Consent process. It’s designed to let you make an informed choice about using an out-of-network surgeon while still protecting you from unexpected bills on everything else. Here’s how it works.
The Waiver
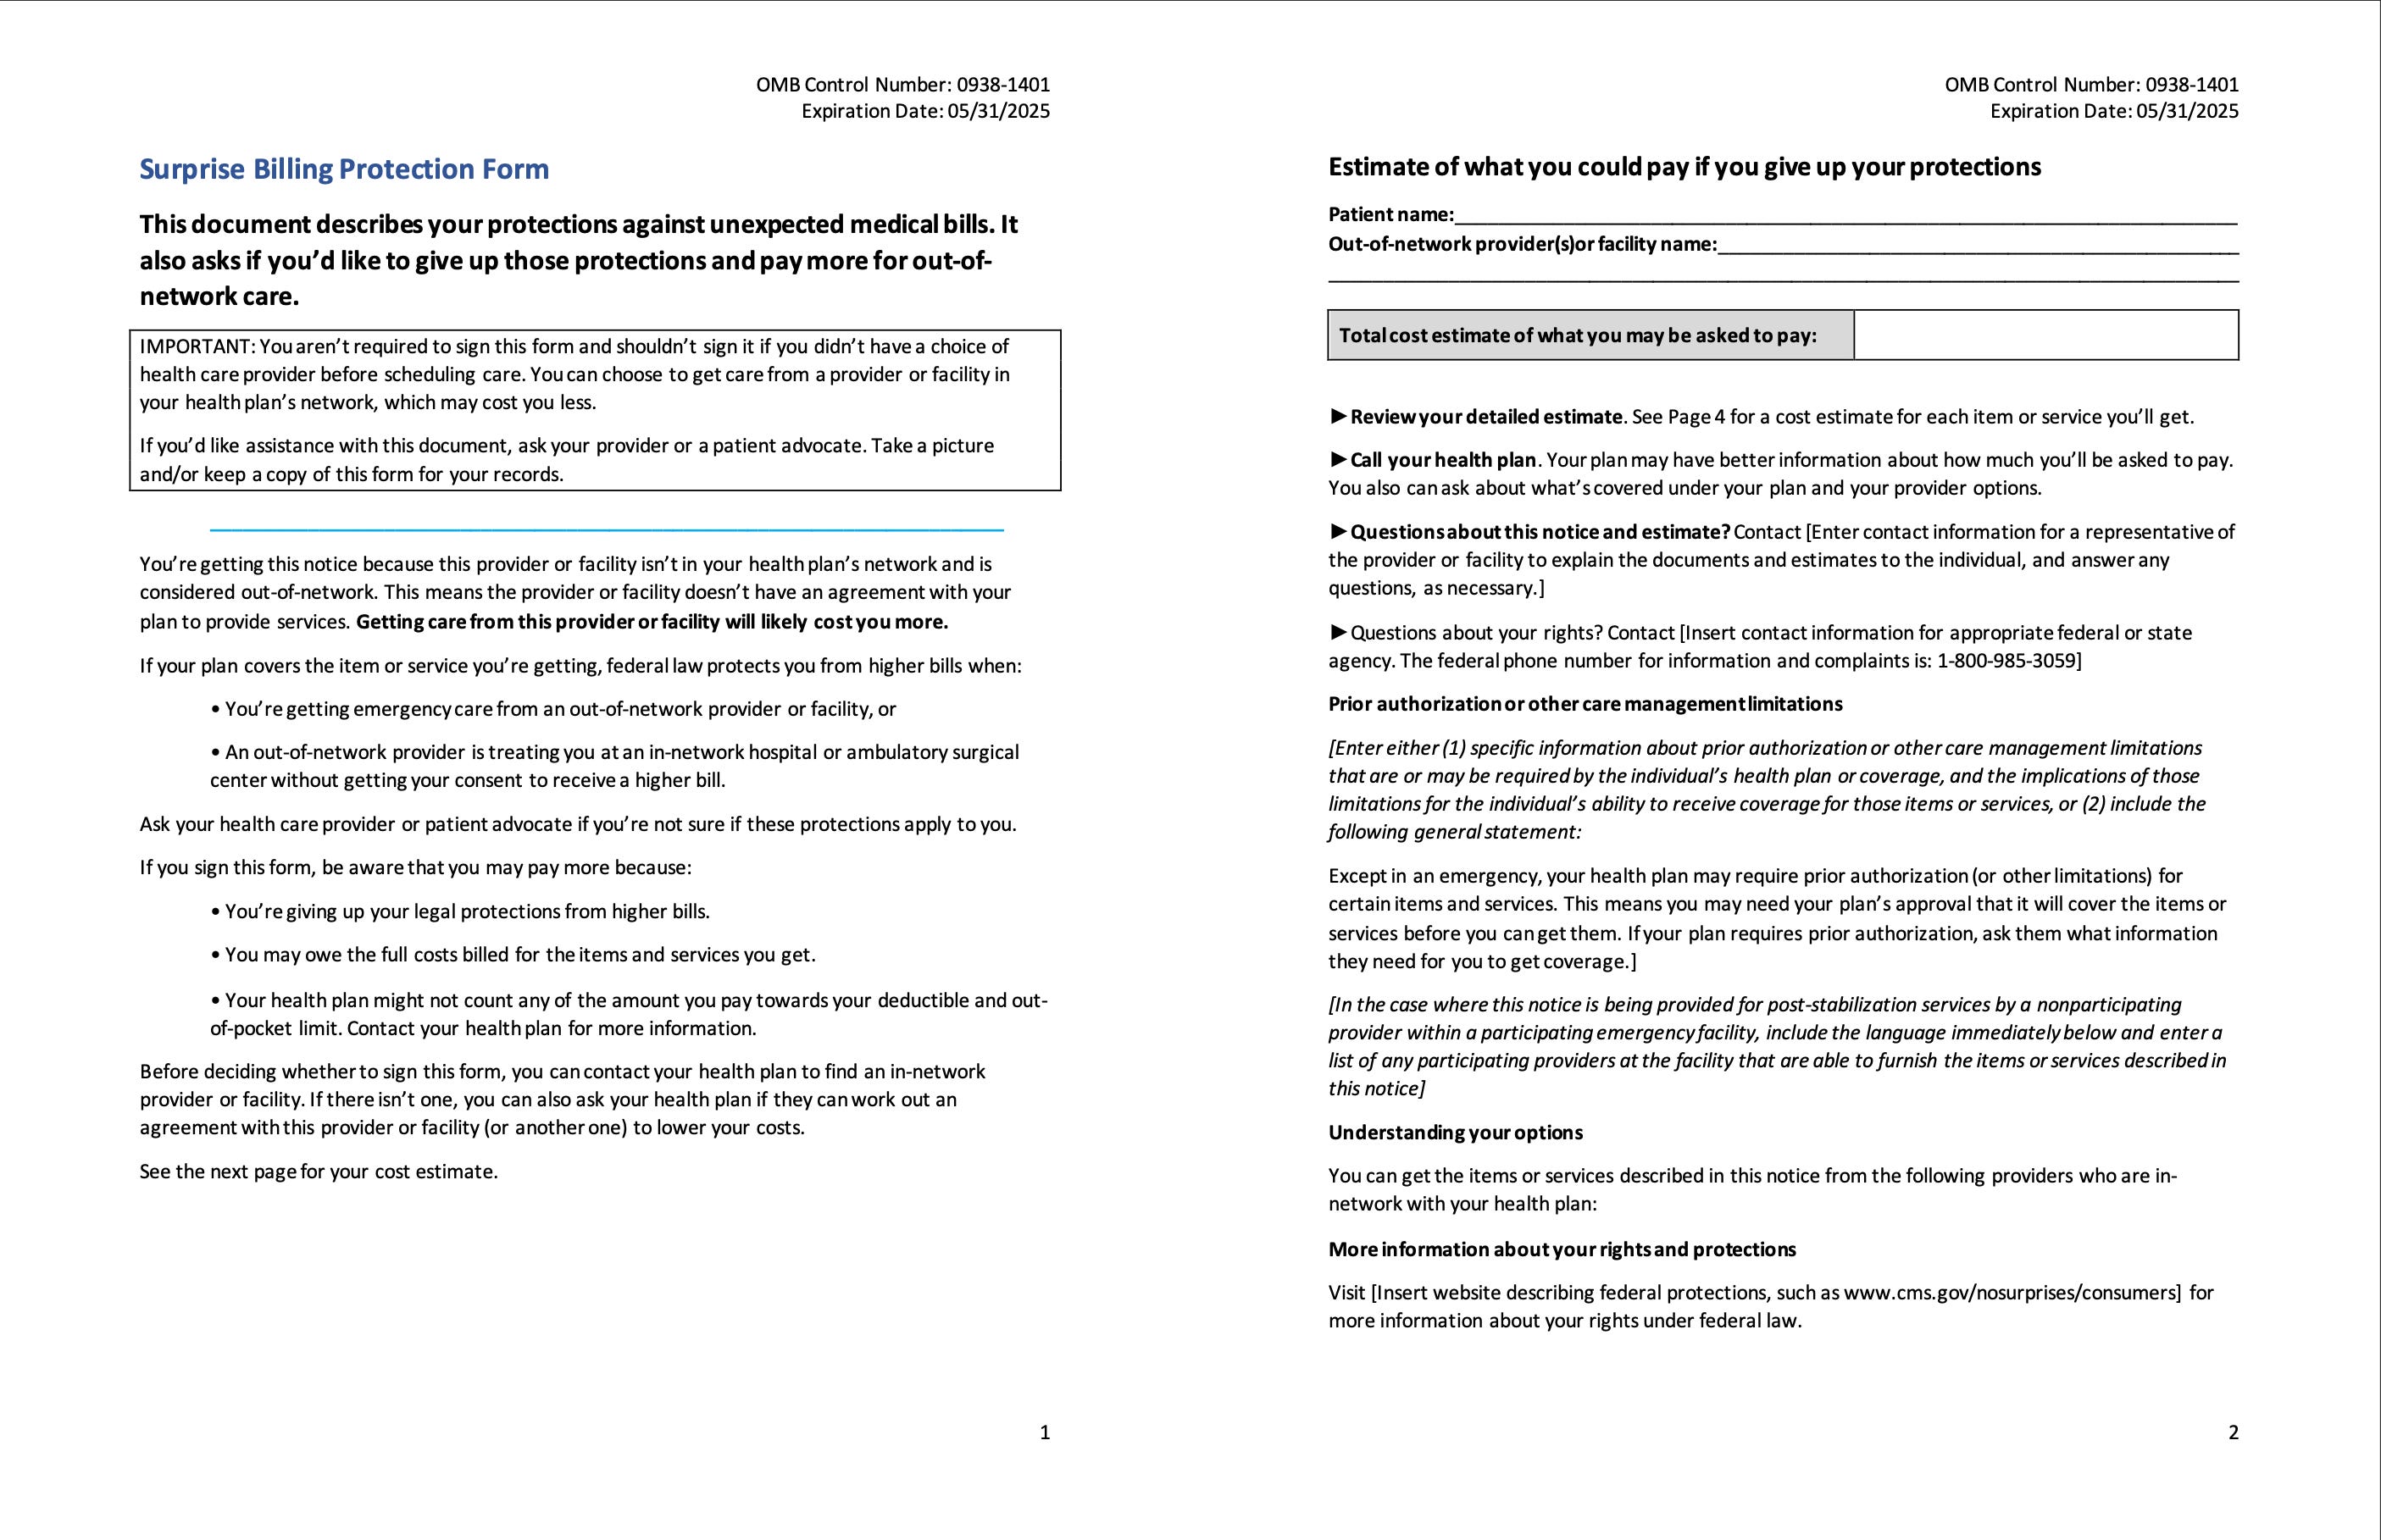
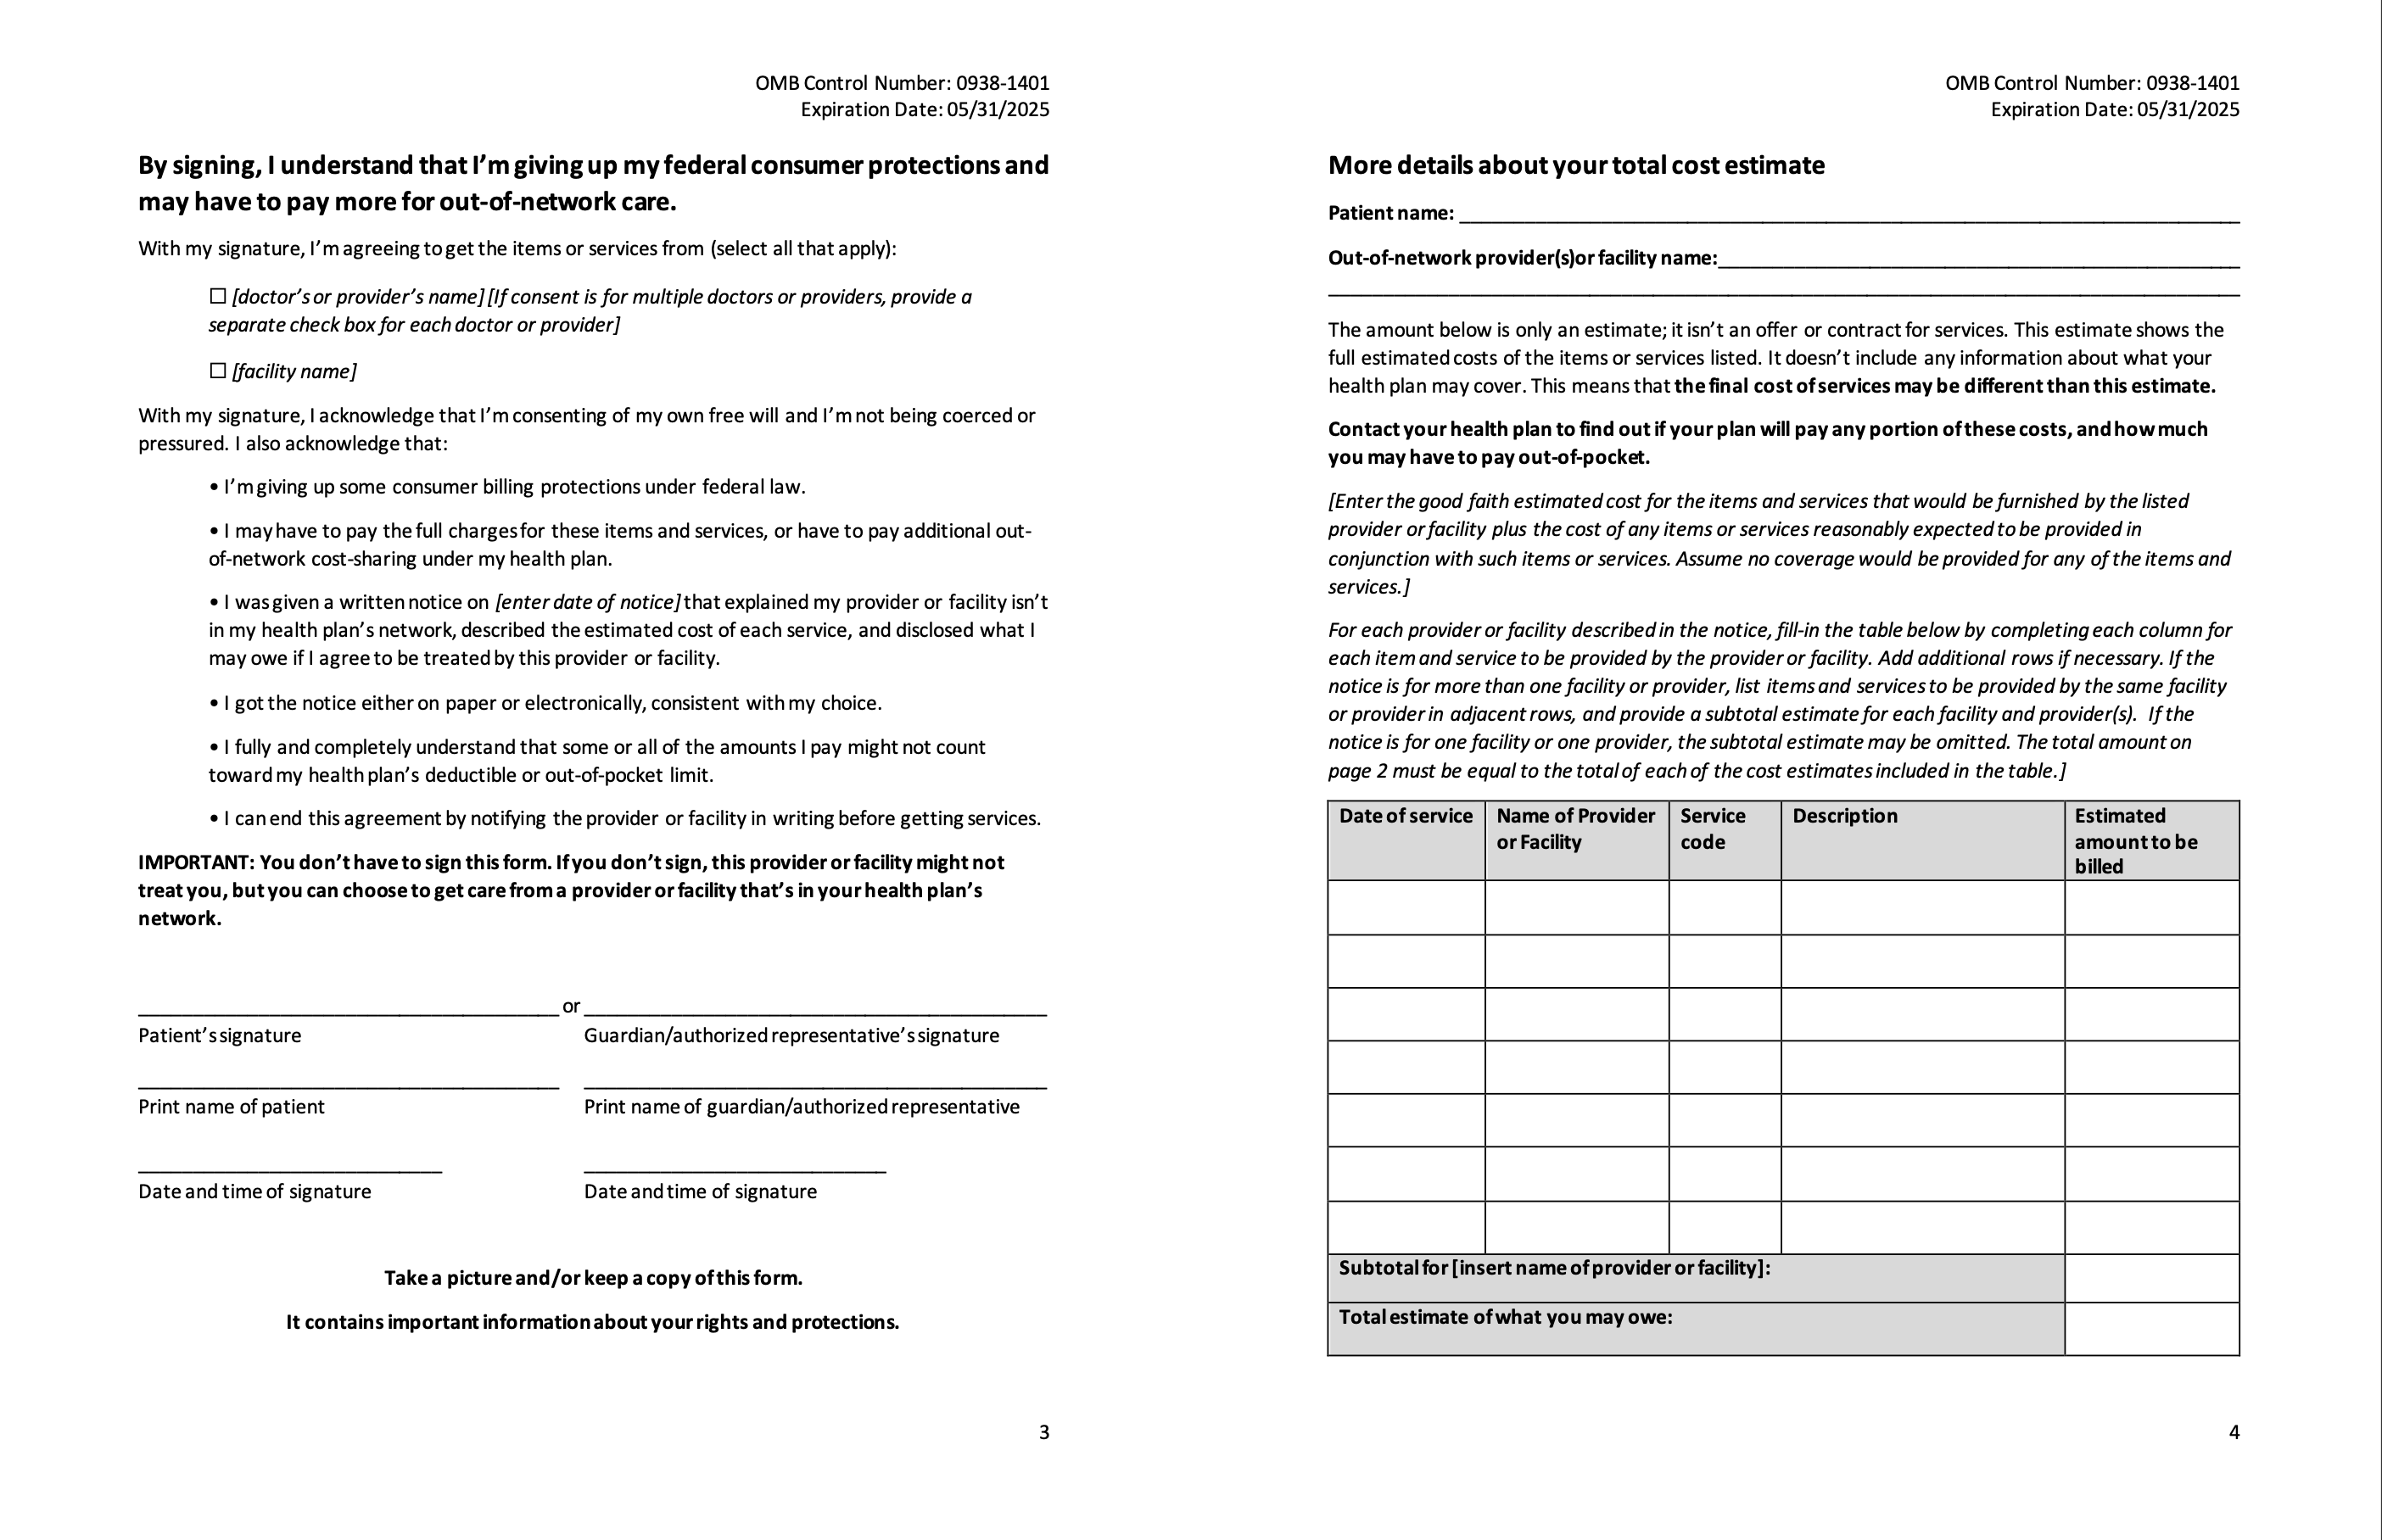
At least 72 hours before your surgery, the surgeon’s office gives you a federally mandated form to review and sign. This form tells you three critical things: that the surgeon is out of network, exactly what they plan to charge, and that you’re accepting financial responsibility for this fee. It provides informed choice ahead of time, instead of surprise bills.
You sign the waiver for the surgeon only. This is important. The waiver doesn’t apply to anyone else.


What Stays Protected
Even though you chose an out-of-network surgeon, the law protects you from balance billing on other services. Your anesthesiologist, pathologist, radiologist, and any assistant surgeon cannot ask you to waive protections. They must bill your insurance and accept what it pays. You pay only your normal in-network copay or coinsurance for these services.
The facility (the hospital or surgery center) is in-network. You pay your regular in-network deductible and coinsurance for the operating room, recovery, supplies - all of it. No surprises there either.
Only the surgeon you specifically chose operates outside those rules because of the informed waiver.
The Payment Process
Most out-of-network surgeons require payment upfront. You pay the full fee before surgery. In return, they give you a detailed Superbill, a document with all the medical codes, diagnosis information, and provider credentials that insurance companies need.
This Superbill is your ticket to reimbursement. You submit it to your insurance company. Some insurers let you upload it through their website. Some require a paper form. There are also companies online that specialize in helping submit the Superbill and other paperwork (a popular one is Reimbursify. Disclosure: none, we don’t have any financial relationship with them or get paid by them).
Understanding Reimbursement
Your insurance calculates something called the “allowed amount” for out-of-network care. This is typically based on one of two methods: a percentage of Medicare rates (often 110-140%) or Usual and Customary rates for your geographic area (often the 80th percentile of what local doctors charge).
The calculation matters. If your surgeon charged $5,000 and your insurer’s allowed amount is $3,500, you’ll pay your out-of-network deductible and coinsurance on that $3,500. You’re responsible for the $1,500 difference, in this example.
Before you commit, call your insurance company. Ask specifically: “How do you calculate allowed amounts for out-of-network surgical procedures?“ Get the answer in writing. This lets you estimate what you’ll actually pay out of pocket.
Making It Work Better
You have leverage at several points. Before surgery, you can request a network gap exception. If you can demonstrate that no in-network surgeon within reasonable distance has the specific expertise you need, your insurer might agree to cover your chosen surgeon at in-network rates. One drawback here, though, is the reimbursement is still capped at the plan's allowed amount, not necessarily the surgeon’s billed fee.
Make sure the facility gets prior authorization. Even though you’re paying the surgeon directly, the hospital needs approval from your insurance to cover their fees. The hospital usually handles this, but confirm it’s done.
The Big Picture
Sometimes you need a specific surgeon. Maybe you have a rare condition. Maybe you need subspecialty expertise. Maybe you’ve researched extensively and know who you want.
The Notice and Consent process gives you that choice while protecting you from surprise bills on everything else. Like the anesthesiologist you never met, the pathologist reading your biopsy, the assistant in the operating room.
You know the surgeon’s fee upfront. You know what’s protected. You can calculate roughly what insurance will reimburse. Then you can decide whether to move forward. This isn’t how it works in a lot of other countries. But it’s transparent. And transparency, at least in US healthcare, counts as progress.